 Veronica BarreraVeronica Barrera
Seleccione para continuar · Select to continue
Mortgages for ITIN · DACA · Self-Employed · California
I'm Veronica. I've worked in lending since 2003, helping Latino families buy homes. I make sure you understand what you're signing, and that nobody takes advantage of you.
Answer 15 questions. In 5 minutes you'll know where you stand.
Get started →Free · No credit impact · 5 minutes
The 3 things on your mind
When someone calls me, they almost always ask the same three things. Here's the short answer. The full one we cover on the call.
It might not be as bad as you think. And even if it's low, there are loans that accept down to 580. If we need to work on it first, I'll tell you exactly what to do and how long it'll take.
There are 3% programs. There's help for the down payment AND closing costs. People qualify for these all the time and don't know it. That's what the quiz is for — to see which ones fit you.
I know how to present a self-employed buyer's income properly. Bank statement loans. 1099. There are paths the big banks won't show you. I will.
In 5 minutes you'll know which of the three you're strongest in, and which one we need to work on.
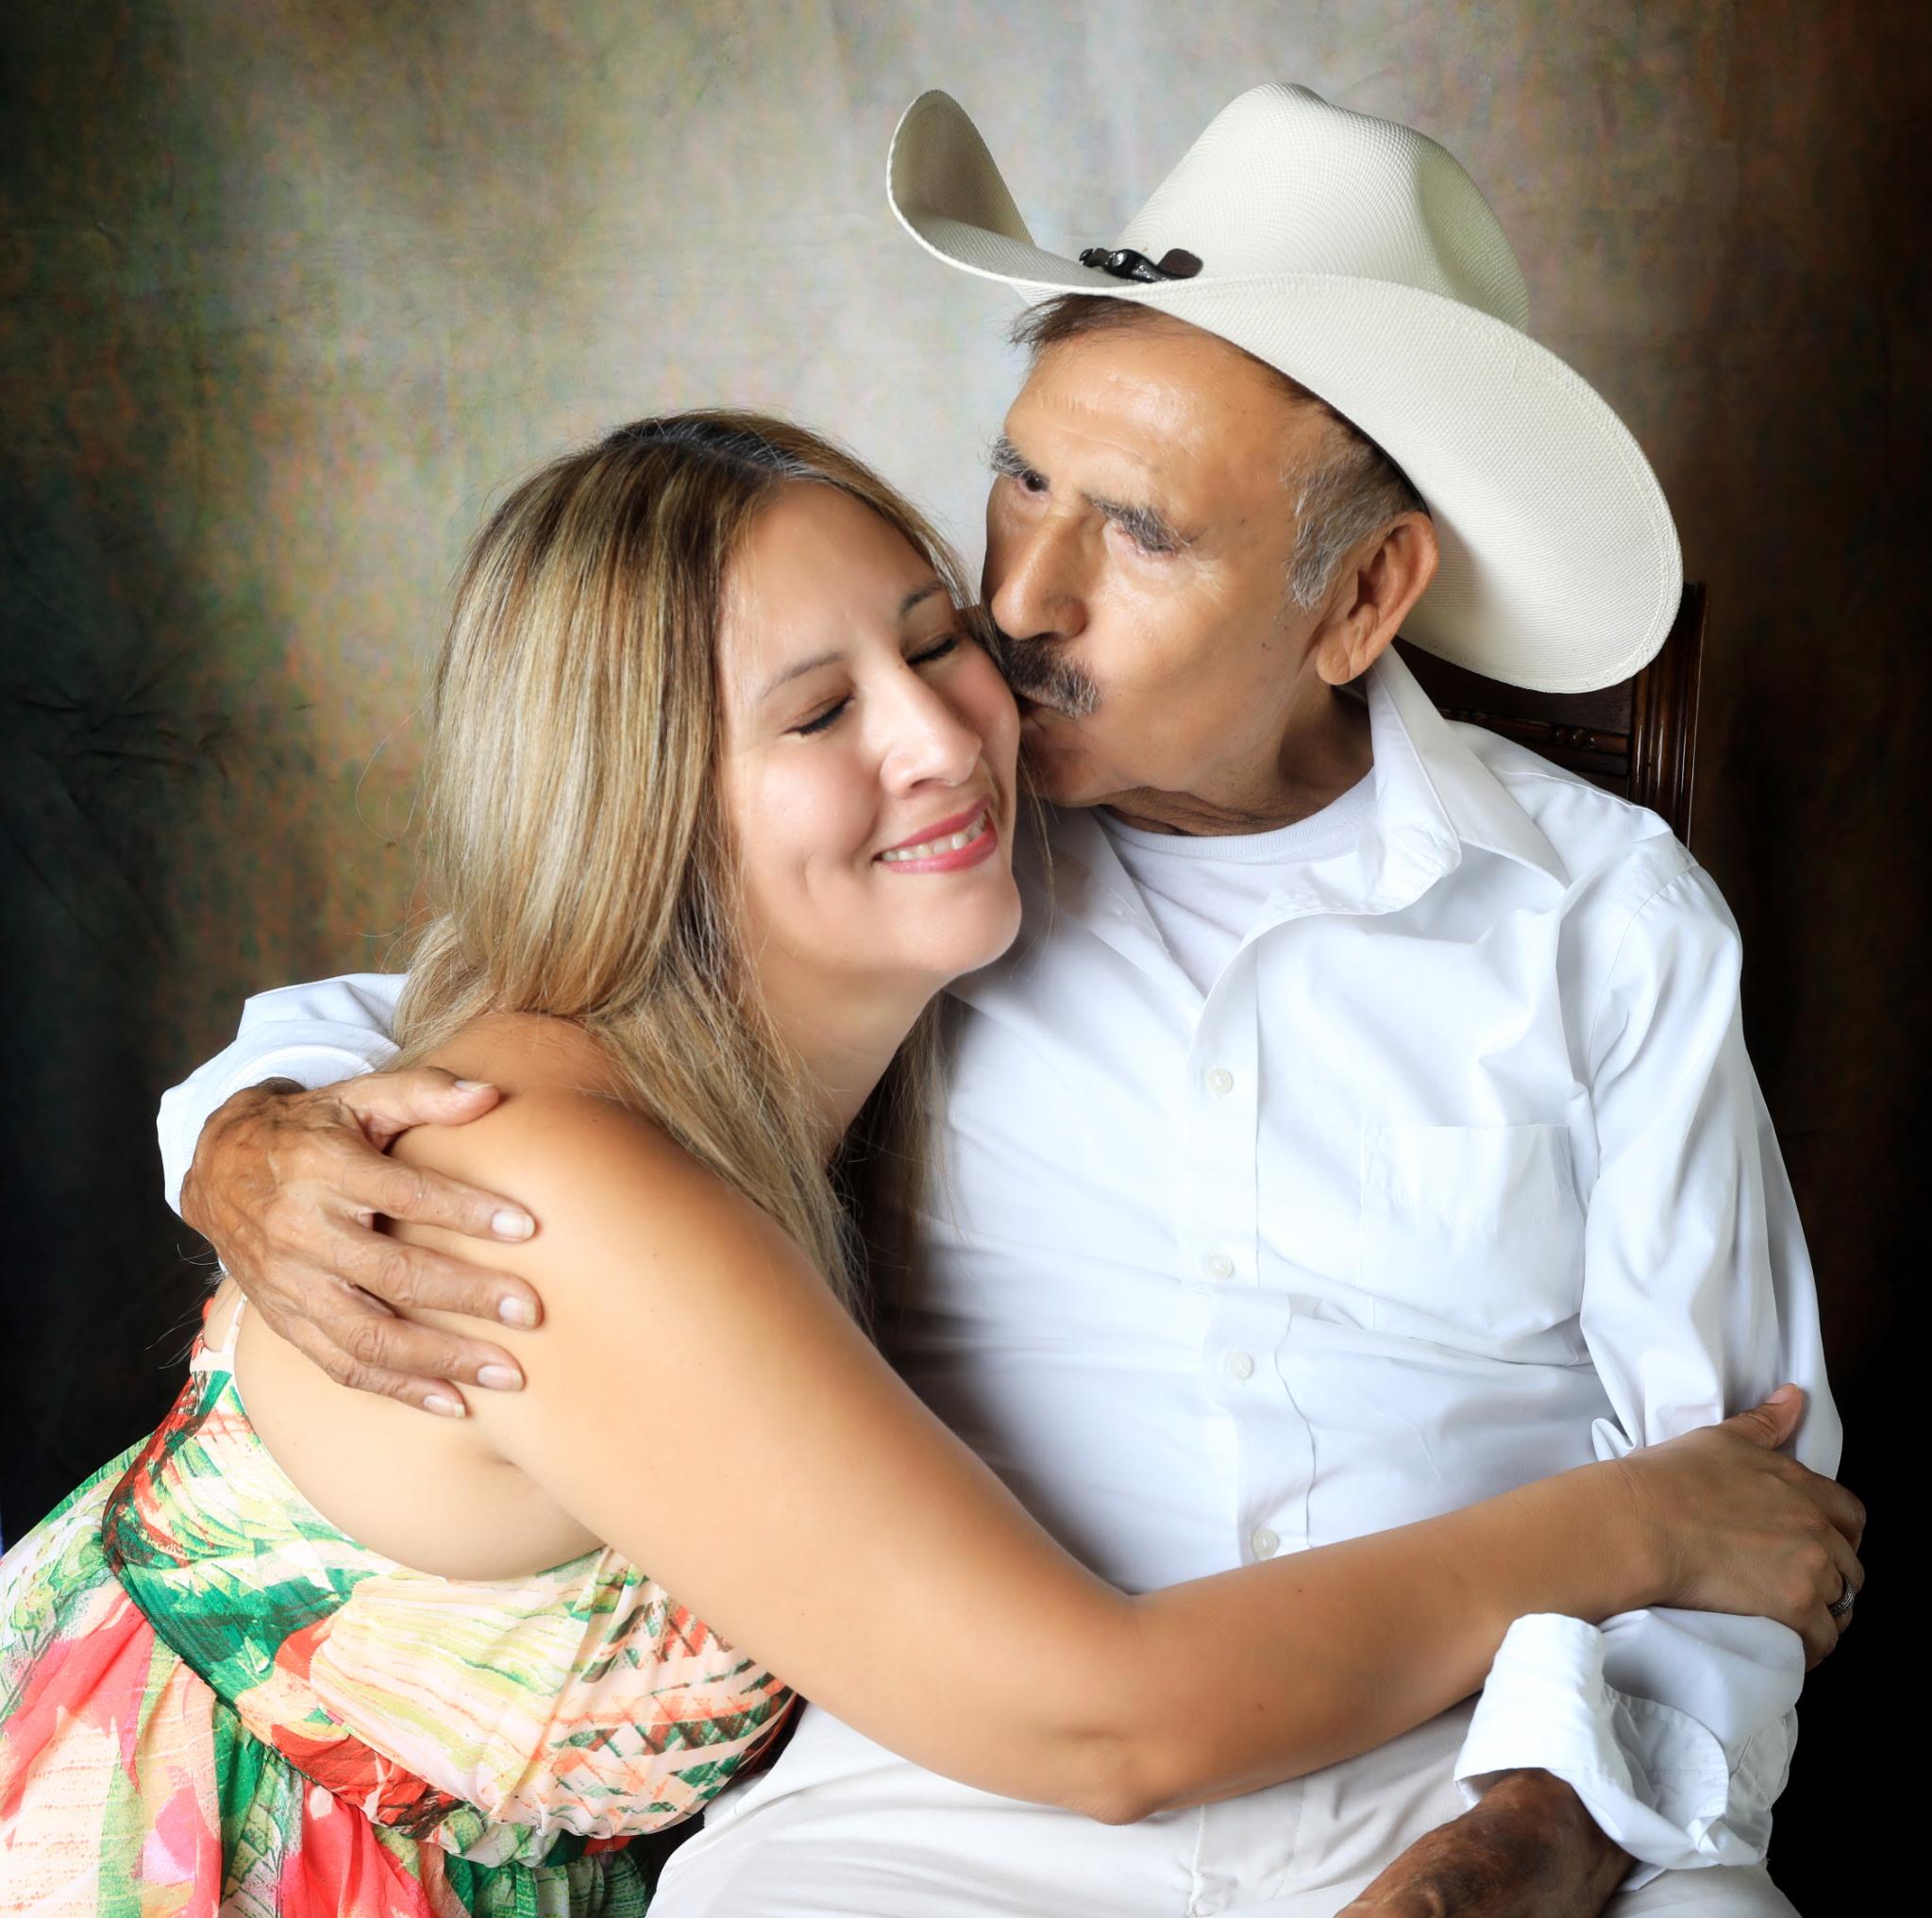
I was born and raised in East LA. When I was 9, we moved to Huntington Park. There are seven of us: six girls and one boy. I'm right in the middle, with my twin sister.
As a little girl, I sold gum and fruit at the park. I helped my parents sell inflatable beach balls. We collected cardboard with them. Sometimes they put us inside the big dumpsters to pull the cardboard out. I never saw my dad take a day off. It was rare to see him sit and watch TV. He was always working.
Little by little, my parents built something of their own. They bought 4 units in East LA. Then houses in Huntington Park and Southgate, and some apartments. To them, owning a home was the American dream. They taught us to save and be responsible. I started working at 16. I translated for them, and I still translate for my dad.
But one day my dad lost an 8-unit building. I was too young to understand what happened. I remember my mom being so, so upset. To this day, my dad tells me the same thing: "The real estate agent lied to me."
I never forgot that.
I started at Chase as a receptionist. Then I became an underwriting assistant. When a loan officer assistant job opened up, the manager said no. He said I was too nice, that I couldn't handle it. I wrote him a letter and slid it under his door. The next morning he called me into his office: "I like your persistence." He gave me the job. When he left, I became a loan officer.
In 2011 I joined Golden Empire Mortgage as a processor. I kept helping families, got my license, and today I'm both a processor and a loan officer. I've seen a loan from every seat: underwriting, assistant, loan officer and processor. I know what the underwriter will look for before they ask.
My office gets a lot of loans other lenders already turned down. That's where I learned to find a way. But what hurts me most is seeing Latino families lose what they worked so hard for, because they signed without knowing what they were signing.
That's why I tell everyone: even if I'm not your loan officer, if you don't understand something, let me help you. Before you sign, call me.
Your parents don't speak English. I grew up translating for mine, and I still translate for my dad. It really bothers me when a bank won't help someone in Spanish. With me, I explain everything in your language. That weight isn't yours anymore.
You were told no somewhere else. There are many loan types for different situations: bank statement, ITIN, FHA, conventional, and more. Big banks often don't do them, or their loan officers don't have the experience. I do.
You're self-employed and you write off everything you can. I get it. But to buy a home you have to show income. We plan that together.
You don't have a Social, but you do have an ITIN. Of course it's possible. They're called ITIN loans. The interest and down payment are higher, but if you put in the work, it can be done.
You have DACA or a work permit and think this is only for citizens. It's not. The rules changed in 2025, but there are still paths. What matters is having a plan from the start.
You want a conversation, not a form. I ask a lot of questions, because your situation is bigger than an application. I see the whole family, not just whoever signs. We're going to find the path, get creative, and see where you really stand.
If today is a no, that doesn't mean it's a no forever. Before you sign, call me.
Answer 15 questions. Walk away knowing four things.
1
A clear score: "Ready," "Almost Ready," or "Your Plan Starts Here." Wherever you are, there's a path.
2
An estimate of your monthly payment with everything included. Plus a slider so you can see how the payment changes at different interest rates. So you come to the call already knowing the numbers.
3
I'll walk you through what matters in your case. If there are assistance programs that fit you, I'll show you which ones. And if there's something we need to fix first, that too.
4
I personally review your result and call you. If today is a no, I tell you why. If it's a yes, I tell you what comes next.
It depends on the loan type and your situation.
If you're a first-time buyer with good credit, it can be as little as 3%. If you're a first-time buyer and your credit isn't great, around 3.5% with FHA. If you're going with an ITIN loan, with my bank it's 15-20%. If you're buying an investment property, 20%.
There are also down payment assistance programs like CalHFA's MyHome and ZIP, and sometimes you qualify and don't even know it. That's why we do the quiz first. To know exactly what fits you.
Possibly yes. With FHA you can qualify starting at 580. It's not ideal, but it can be done.
The important thing is to look at your whole situation, not just the number. Sometimes the score looks bad but there are things we can fix quickly. Other times we need a few months of work before applying. And other times you're more ready than you thought.
That's why the quiz. In 5 minutes we know where you really stand.
Nothing. I don't charge you to work with you.
If we work together a month, six months, a year, and in the end you decide to go with someone else, all that time was free. I get paid when I help you close a home or refinance. That's it.
I'm straightforward: I show you exactly what your loan costs, and I would never overcharge you.
Yes. But the path has changed.
Since 2025, FHA no longer accepts DACA or people who aren't permanent residents. I had a client on a work visa. We closed his FHA loan one week before the rule changed. He told me: "We would have never bought a house if it wasn't for you."
The good news: conventional loans have competitive rates and 3% down programs. If your work permit (EAD) is about to expire, you'll need to renew it before you apply.
Yes, it can be done. What you both need to know is that the loan is going to be an ITIN loan, with higher interest and a higher down payment. With my bank, 15-20% down.
It's not the cheapest loan, but it's real, it exists, and many Latino couples buy this way. The important thing is to go into this with your eyes open, knowing the numbers from the start.
Hopefully he's depositing that cash in the bank, because that's where it all starts.
There's a loan called a Bank Statement Loan. With this loan we don't look at your taxes, we look at the deposits coming into your account. Usually we need 2 years of bank statements.
The other option is to start reporting that income on your taxes. It'll take longer to buy a home, but it can also be done. The most important thing in either path is to document where the money comes from.
It depends on where you are right now. If your credit is in order, your down payment is ready, and your work is stable, you can close in 30 to 45 days from when you apply.
If we need to work on something (raise your credit, save more for the down payment, wait until you hit 2 years self-employed), it can be 3 to 12 months. The good part is when we make the plan, you know exactly what to do and how long it takes.
The people who start early always get there faster than the people who wait until they feel "ready." That's why it's worth doing the quiz even if you don't want to buy tomorrow.
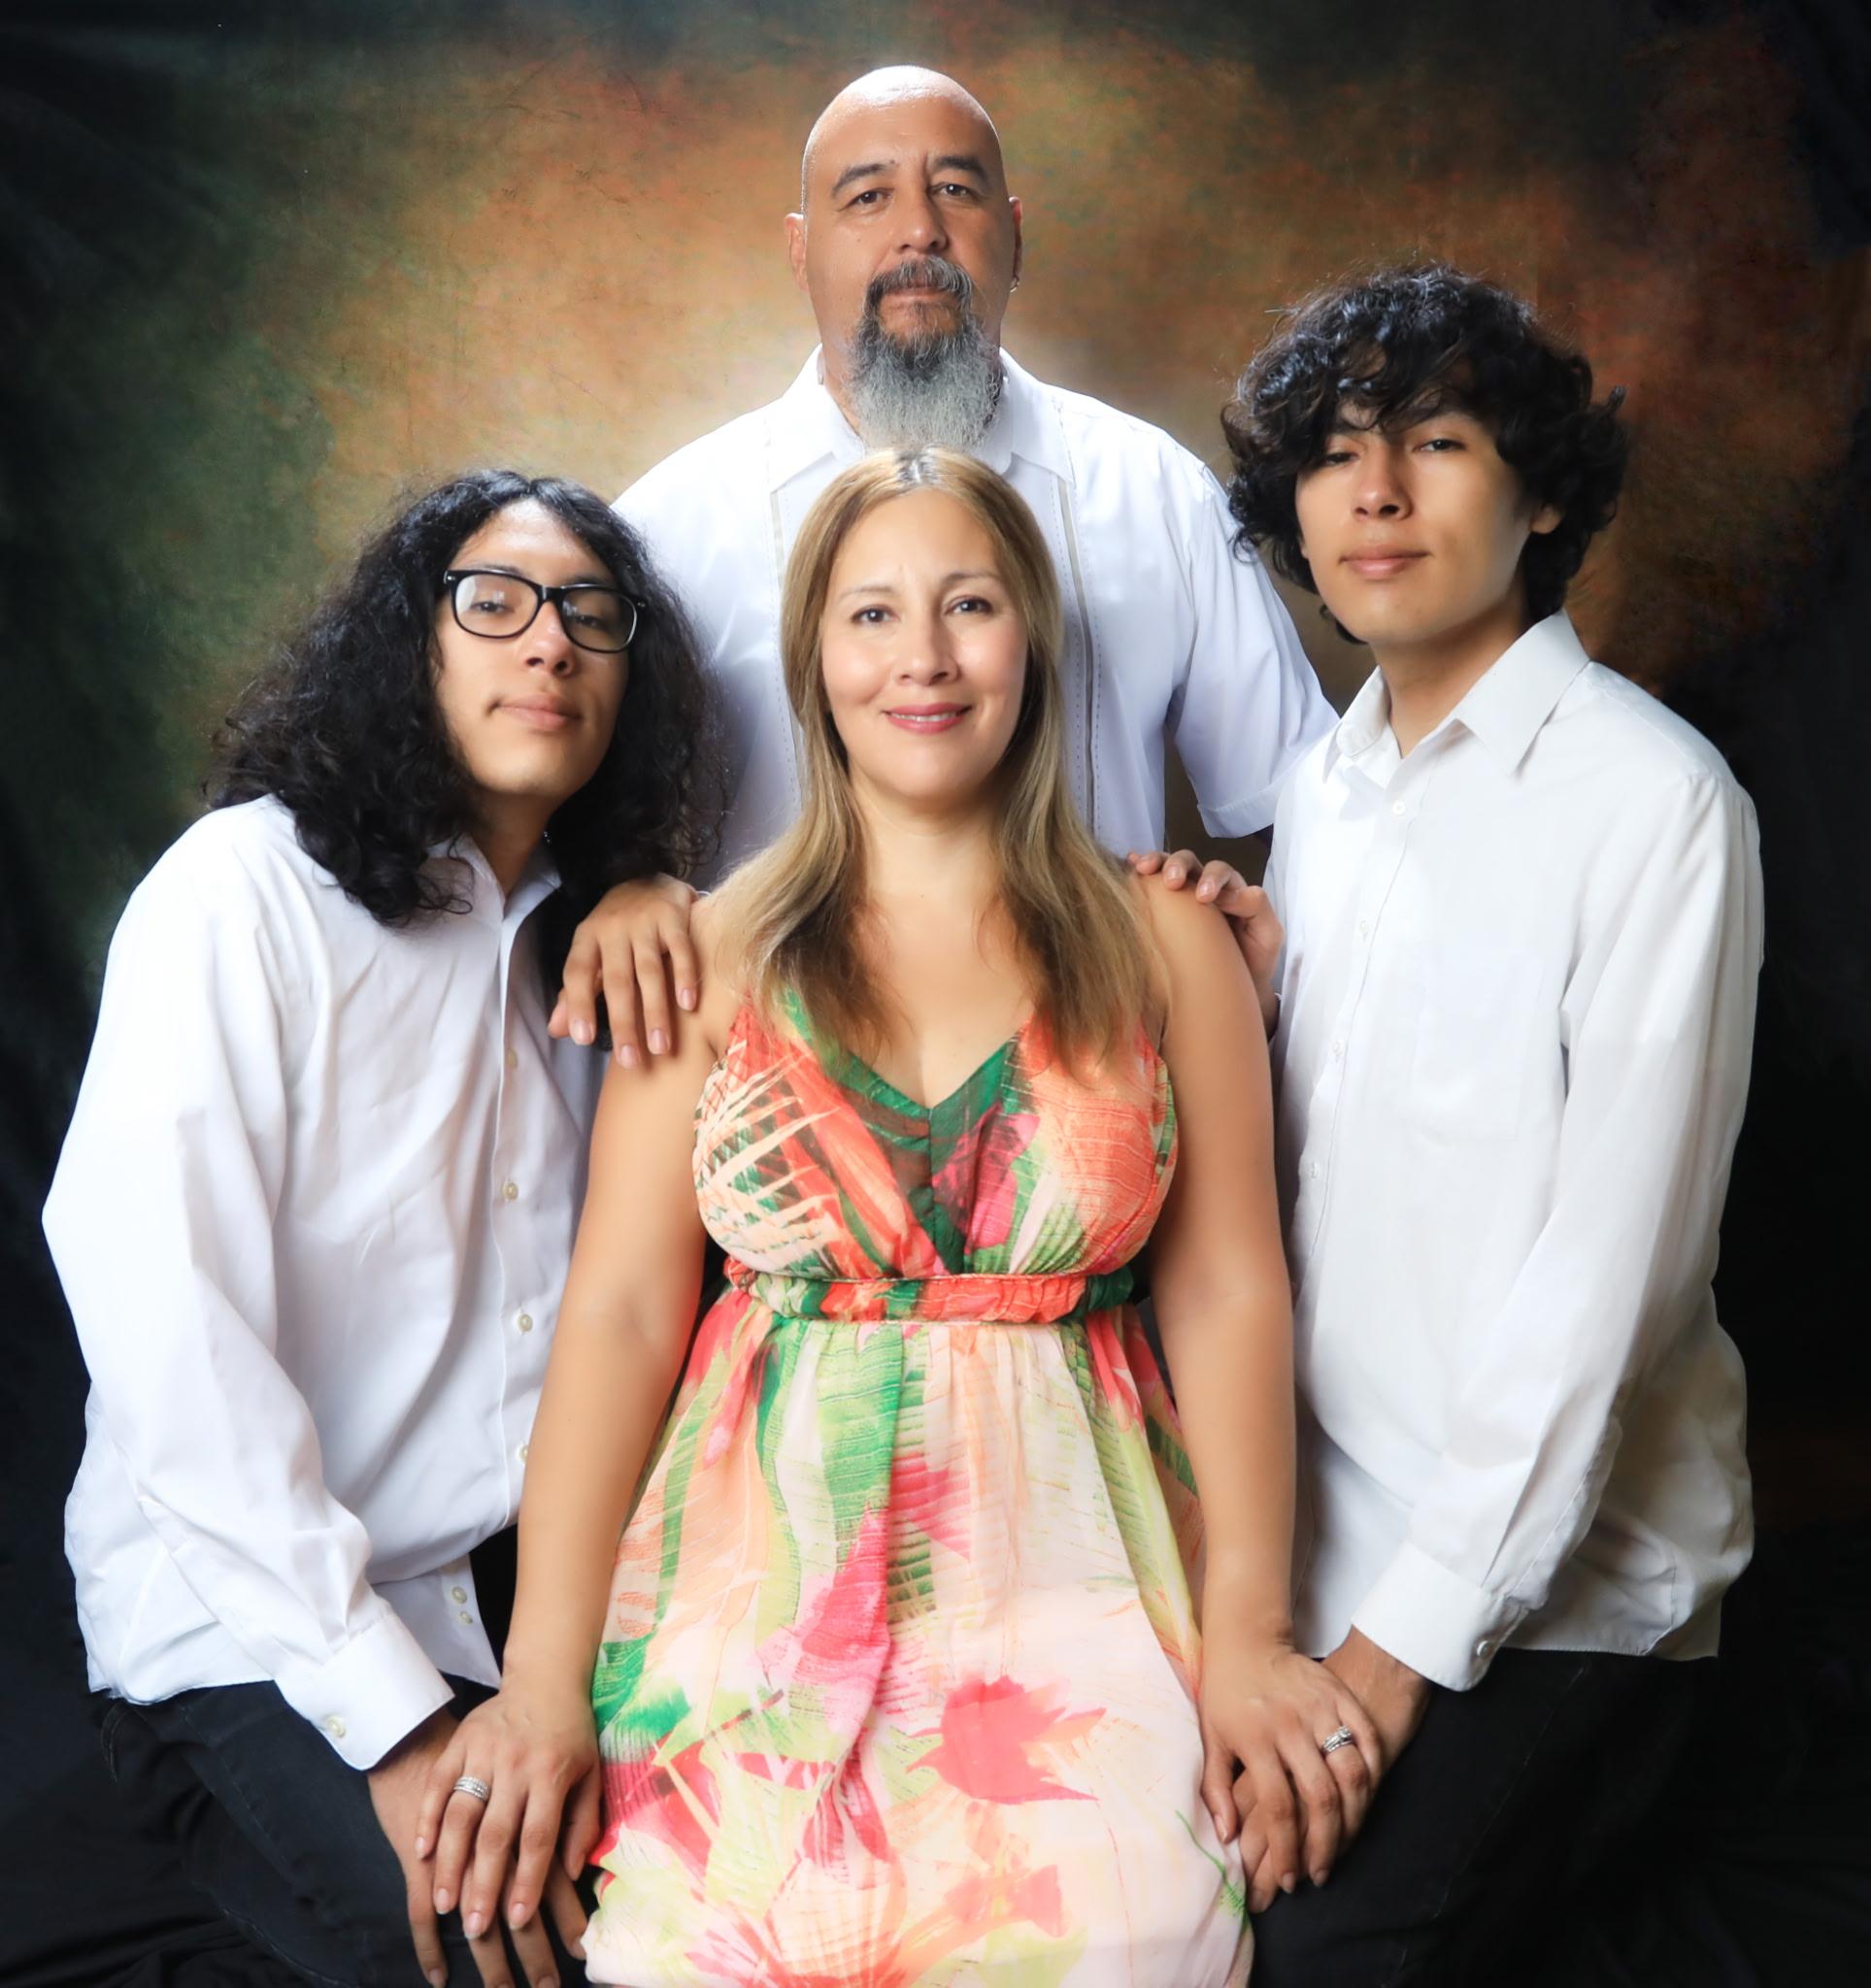
When I moved out of my parents' house, people told me I'd never be able to pay $1,200 in rent. I did. We rented for many years, and I thought I'd never buy. But I bought my house, and I wish I had done it sooner.
Your first step is 5 minutes. No commitment, no effect on your credit, no calls you didn't ask for.
Free · No credit impact · 5 minutes